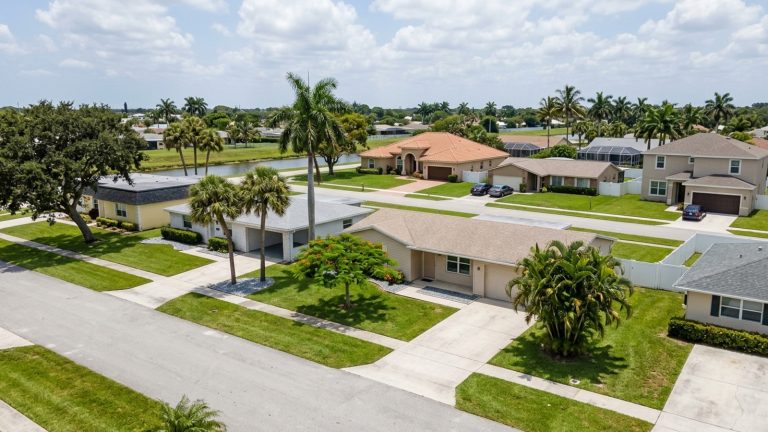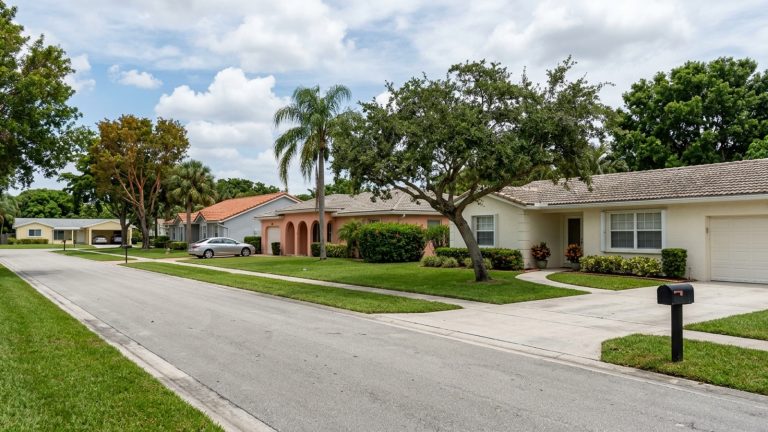

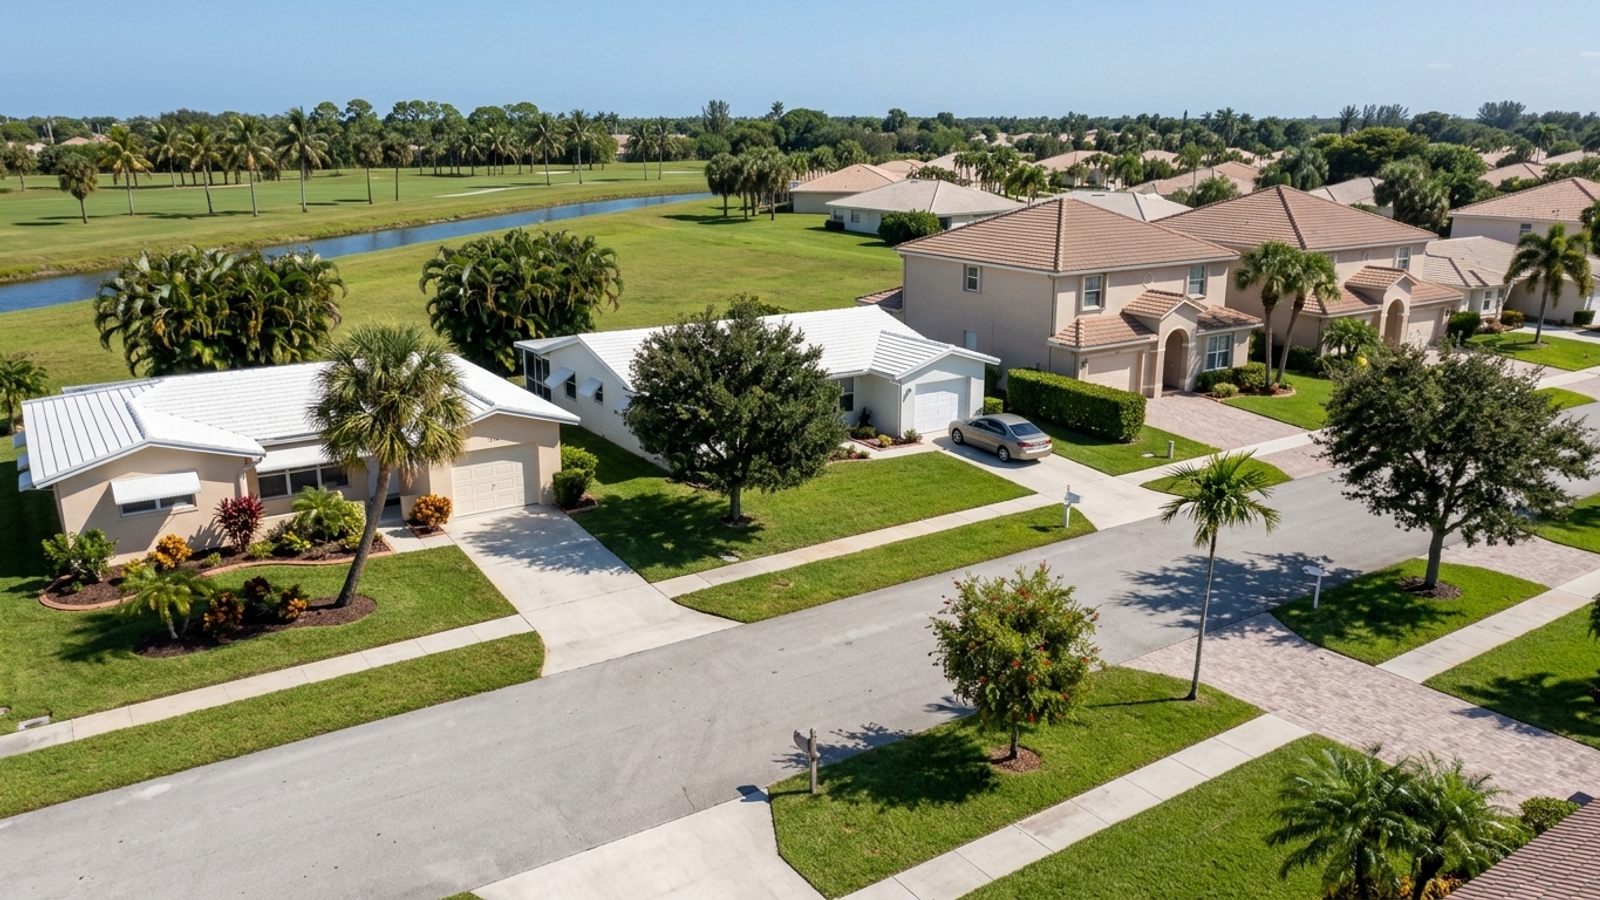
The median home price for those buying a home in Tamarac, FL sits at roughly $314,792. That’s more approachable than a lot of Broward County, but coming up with a down payment and closing costs is still a real obstacle for most renters.
The good news is that state and local programs exist specifically to close that gap. With about 641 homes currently on the market in Tamarac, there’s inventory to work with – and if you know which assistance programs you qualify for, the math on buying changes considerably.
First-Time Home Buyer Programs Available in Tamarac, FL
Buyers in Tamarac can pull from two layers of help: statewide Florida Housing programs and Broward County-specific initiatives. Together they cover down payment and closing costs through a mix of deferred second mortgages and grants.
How much you get depends on which program you use and where your household income falls. Certain local programs can also be layered with federal loan types, which reduces your out-of-pocket costs at closing even further.
State-Level Options in Florida
The Florida Housing Finance Corporation runs several statewide programs, including Hometown Heroes and FL Assist. Both are designed to deliver down payment and closing cost funds to eligible buyers.
Hometown Heroes relaunched its 2026-2027 funding cycle in July 2026 with $50 million available. By mid-September 2026, roughly $25 million to $35 million remained. That’s not a scare tactic – it’s just a reason not to wait.
Broward County and Tamarac Programs
Broward County has its own layer of help through the Homebuyer Purchase Assistance (HPA) Program, which offers up to $80,000 as a 0% interest deferred-payment second mortgage for income-eligible buyers. That’s a significant number.
There’s also the First Home 4 U program through the Housing Finance Authority of Broward County, which offers up to $10,000 as a deferred second mortgage or a 3% grant paired with an assisted-rate first mortgage.
Federal Mortgage Options
FHA, VA, and USDA loans pair well with the local assistance programs listed above. FHA loans stay popular with first-time buyers because the down payment floor is lower and the credit guidelines are more flexible.
VA loans allow zero down for eligible veterans and service members. USDA loans are worth asking about, but because Tamarac is largely urban and suburban, you’ll want to verify whether a specific property falls within eligible boundaries – those loans are intended for rural areas.
Grants and Down Payment Assistance in Florida
The Florida Hometown Heroes program gives you 5% of your first mortgage loan amount toward down payment and closing costs. The minimum assistance is $10,000 and it caps at $35,000.
That money comes as a 0% interest, non-amortizing 30-year deferred second mortgage. It’s not forgivable – you’ll repay it when you sell, refinance, or stop using the home as your primary residence.
Grant Amounts and Assistance Types
FL Assist offers up to $10,000 in down payment help. Broward County’s HPA program goes much higher, up to $80,000, and that amount becomes forgivable after a 15-year affordability period.
If a purchase still doesn’t pencil out after those programs, the Broward County CDBG Purchase Assistance Program can sometimes fill what’s left. It’s worth comparing all of these against your specific purchase price and loan size before committing to one path.
Low-Down-Payment Options
You don’t need 20% to buy in Tamarac. Conventional loans for first-time buyers can require as little as 3% down; FHA loans require 3.5%.
Stack either of those with FL Assist, and your required cash at closing drops considerably – often to the point where the assistance covers the entire down payment requirement.
How to Apply for Florida Grants
You can’t apply for Florida Housing programs directly through a state or county website. The application goes through a state-approved participating mortgage lender.
Your lender reviews your financial profile, identifies which programs you qualify for, and submits the application on your behalf. Once your loan is approved, they reserve your funds in the state system.
Who Qualifies for These Programs
For Hometown Heroes and FL Assist, the 2026 Broward County income limit is $145,820 for a one- or two-person household. For households with three or more people, that limit rises to $152,160.
Eligibility comes down to income, household size, and first-time buyer status. A family might qualify for state help and still exceed the income cap for a county grant – so it’s worth checking both.
Income Limits in Broward County
The Florida Housing Finance Corporation uses median family income figures to set eligibility thresholds. For Broward County in 2026, the median family income is $102,500.
County programs tier off that number. A “Low” income household (80% of median) can earn up to $70,950 to $150,131 depending on family size. A “Moderate” household (120% of median) falls between $106,440 and $225,197. Those ranges are wide, so where you land in them matters.
Credit and Debt Guidelines
Most state and county assistance programs require a minimum credit score around 640. Your lender will also look at your debt-to-income ratio – that’s your gross monthly income measured against your total monthly debt obligations, including the new mortgage.
Most programs cap that ratio at 45% or 50% depending on the loan product. If you’re carrying heavy car or student loan payments, that cap can limit how much house you qualify for.
What Disqualifies Applicants
Owning a primary residence within the past three years generally disqualifies you from first-time buyer status. Exceeding the income cap for a given program also takes you out of the running for that specific source of funds.
Buying an investment property or a second home is an automatic disqualifier. Every program here requires the home to be your primary residence – there’s no flexibility on that.
How Much House You Can Afford in Tamarac
Homes in Tamarac spend a median of roughly 84 days on the market before selling, and the average sale-to-list price ratio is 96.45%. Buyers have a small window to negotiate, but it’s not zero.
Figuring out your real budget means looking at gross income, expected interest rates, property taxes, and HOA fees. Tamarac has a lot of condo and townhome communities, so HOA dues are a regular line item in the monthly math – not an afterthought.
Required Salary by Home Price
To afford a $300,000 to $400,000 house, your required salary depends on your existing debt and the current interest rate environment. A buyer with no other debt might qualify for a $300,000 home on a $70,000 salary, assuming a favorable interest rate.
High student loan or car payments change that calculation. More debt means you need more income to keep your debt-to-income ratio within qualifying range for the same loan amount.
The 3-3-3 Rule for Buying
The 3-3-3 rule is a straightforward budgeting guideline. It suggests saving 3% of the purchase price for the down payment and another 3% for closing costs.
The third “3” means keeping three months of mortgage payments in reserve after you close. That cushion matters – it covers unexpected repairs or an income disruption during your first few months in the house.
Local Price Context in Tamarac
Tamarac’s mix of single-family homes and condominiums produces a median sale price of about $314,792. Prices shift depending on the specific ZIP code – 33321 is the most commonly cited area for the city – and single-family homes typically run higher than condos. If you’re buying a condo, monthly maintenance fees are part of the true cost of ownership.
Down Payment Requirements and Buying Power
On a $300,000 home, a 3% conventional loan requires a $9,000 down payment. FHA at 3.5% brings that to $10,500. Neither figure includes closing costs, which typically add another 2% to 5% of the purchase price.
State and county assistance programs can cover both, letting you keep your savings in the bank.
Minimum Down Payments by Loan Type
Conventional loans for first-time buyers start at 3% down. FHA loans require 3.5%. VA loans allow zero down for qualifying military members.
Your lender will help you decide which structure makes the most financial sense. Down payment size directly affects whether you’re paying private mortgage insurance and how much that insurance adds to your monthly payment.
What a $10,000 Down Payment Buys
With $10,000 saved, you have enough to cover the minimum 3% down payment on a home priced up to roughly $333,000 – which aligns well with Tamarac’s median sale price. That’s not nothing.
The catch is that $10,000 doesn’t leave much for closing costs. Buyers in this position should look at FL Assist to handle closing expenses so their savings can go entirely toward the down payment.
Funding a $300,000 House
Buying a $300,000 property means balancing the down payment, closing costs, and ongoing monthly obligations. If you use the Hometown Heroes program on a $300,000 loan, you’d receive $15,000 – 5% of the loan amount – to apply toward upfront costs.
For buyers who can handle the monthly mortgage but don’t have a large lump sum sitting in savings, that’s exactly the kind of bridge these programs are designed to provide.
Tax Credits and Participating Lenders
Florida Housing assistance only flows through a network of approved lenders. You can’t get it directly from the state, and not every lender is authorized to originate these loans.
Beyond direct grants, there are a few other tools worth knowing about.
Working with Participating Lenders
Approved lenders know the documentation requirements and timelines for both Florida Housing and Broward County programs. They’ll pull your credit, verify your income, and match you with the right assistance.
It’s worth talking to more than one. Grant amounts are standardized by the state, but lender fees and interest rates aren’t – those can vary between institutions.
Tax Incentives for First-Time Buyers
Florida has no state income tax, so state-level income tax credits for buyers don’t apply here. That said, ask your lender about available federal tax incentives and local property tax exemptions.
Florida does offer a homestead exemption that reduces the assessed value of your primary residence for property tax purposes. Filing in your first year of ownership lowers your annual tax bill – it’s a simple step that’s easy to miss.
Using Mortgage Credit Certificates
A Mortgage Credit Certificate (MCC) lets first-time buyers claim a dollar-for-dollar federal tax credit for a portion of the mortgage interest paid each year. Florida Housing has offered MCCs in the past, but availability depends on funding.
Ask your lender whether an MCC program is currently active and whether it makes sense given your tax situation.
How to Apply as a First-Time Buyer in Tamarac, FL
Before you start touring homes, get your financial documents in order. You’ll need recent pay stubs, two years of tax returns, and current bank statements.
Programs like Hometown Heroes run on limited funding pools. Applying early in your home search – not after you’ve found a house you love – is the only way to make sure that money is still there when you need it.
Application Checklist
Gather your W-2s, tax returns, and government-issued identification first. Then contact a state-approved lender to get pre-approved for a mortgage.
The lender will verify your household size and income against the Broward County limits and confirm your eligibility. Once you’re pre-approved, you can start looking at homes with a real estate agent.
Estimating Your Monthly Costs
Your monthly payment includes principal, interest, property taxes, and homeowners insurance. For illustration only: at a 6% interest rate, the principal and interest on a $300,000 loan runs roughly $1,798 per month.
In Tamarac, add HOA fees on top of that – they’re common across many local neighborhoods and condo buildings. High HOA dues reduce the total loan amount you’ll qualify for, so they belong in your budget from the start.
Where to Start Locally
Get pre-approved by a lender who handles Florida Housing and Broward County programs. That conversation will tell you exactly how much assistance you qualify for before you’ve spent a weekend walking through houses.
Once you know your number, you can focus your search on Tamarac ZIP codes like 33321 or 33319 that fit your price point.
Frequently Asked Questions
Previous homeownership within the last three years generally disqualifies you. You’ll also be disqualified if your household income exceeds the Broward County limits – for example, $145,820 for a two-person household under the Hometown Heroes program. Buying an investment property instead of a primary residence is another disqualifier.
Tamarac buyers can access the Florida Hometown Heroes program, which provides 5% of the first mortgage amount up to a $35,000 maximum. Broward County also offers the Homebuyer Purchase Assistance (HPA) Program, which can provide up to $80,000 as a deferred second mortgage.
For a $300,000 house, the minimum down payment is $9,000 using a conventional loan with a 3% requirement. An FHA loan at 3.5% down brings that to $10,500.
It depends on your current debt and interest rates, but a salary of around $70,000 to $90,000 is typically needed for this price range. Buyers carrying high car payments or student loans will need a higher income to keep their debt-to-income ratio within program limits.
You apply through a state-approved participating mortgage lender, not directly through a government office. The lender reviews your income, checks it against Broward County limits, and reserves the funds in the state system when your loan is approved.
Yes. Programs like Hometown Heroes structure the assistance as a 0% interest, non-amortizing 30-year deferred second mortgage that is not forgivable. You’ll repay the funds if you sell the home, refinance, or stop using the property as your primary residence.