
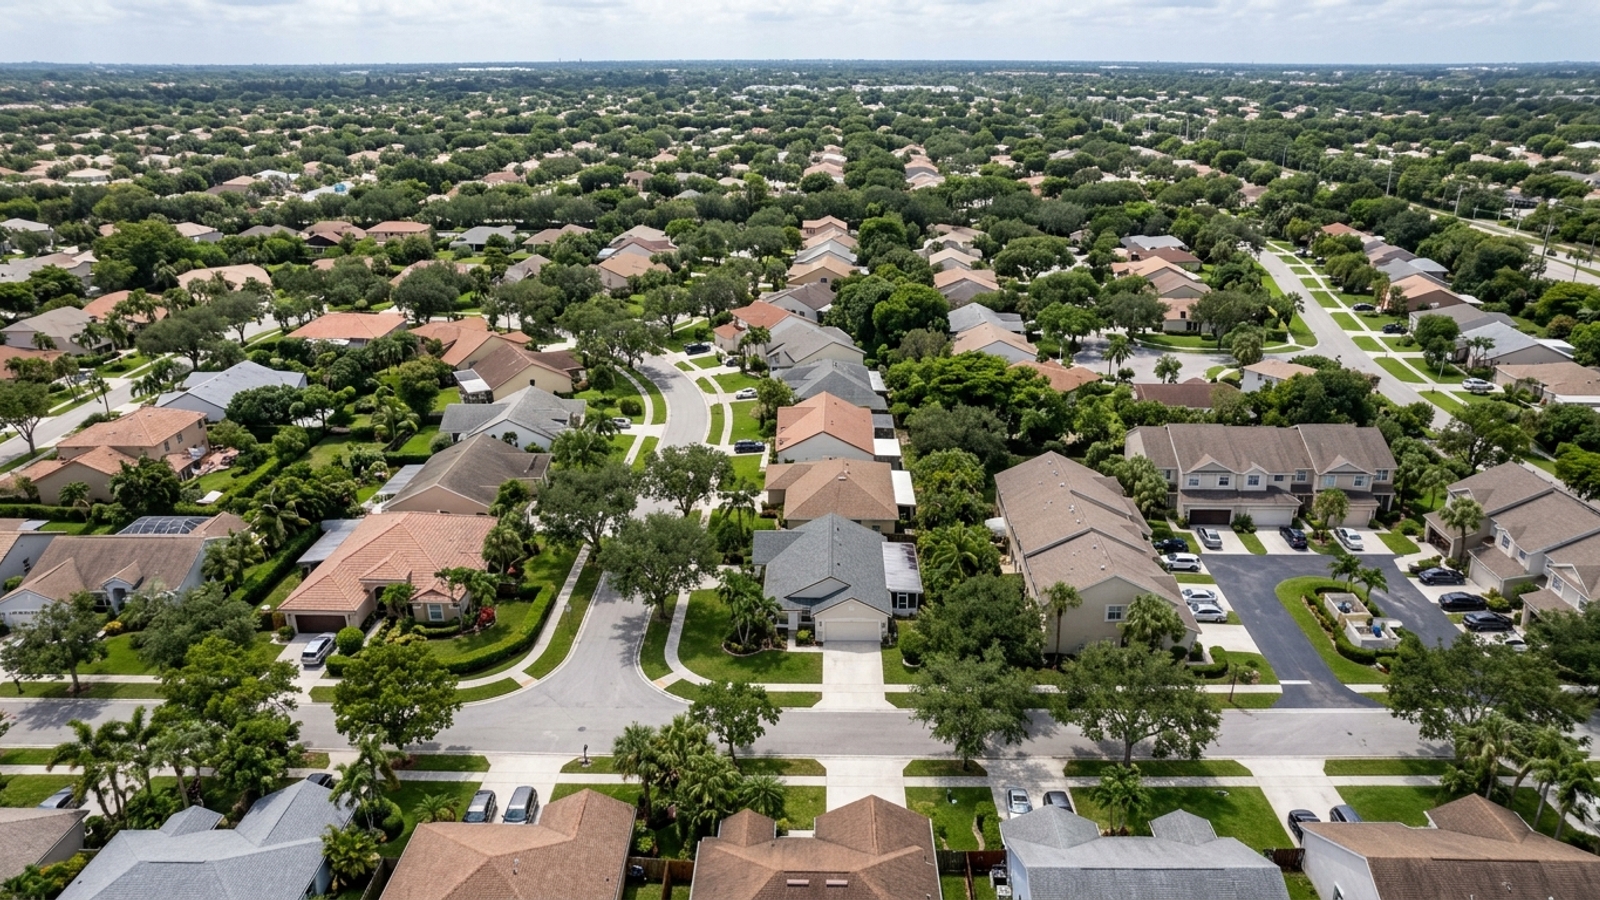
The median home sale price in Tamarac, FL sits around $315,000 right now. With 641 homes currently on the market, first-time home buyers in Tamarac, FL have real options – but what you can afford depends just as much on your interest rate as it does on that price tag.
Rates dictate purchasing power. Whether you’re buying a townhouse near the golf courses or selling a single-family home you’ve owned for years, understanding how lenders price their loans will help you make smarter financial decisions.
How Mortgage Rates Work Today in Tamarac
Mortgage rates don’t sit still, and the numbers you see on national news rarely match what a local lender will offer you. Lenders reprice daily based on bond markets, inflation data, and economic reports – so a generic online tracker gives you a rough estimate at best.
Your personal financial profile and the specific property you’re buying will move those numbers around considerably.
Where to Find Your Exact Rate
The only way to know what it costs to borrow money right now is to get a same-day quote or a Loan Estimate directly from a lender. Those documents reflect your actual credit profile, the home’s price, and your down payment – not some national composite. A static online average is a starting point, not a budget.
Why Rates Change Daily
Banks and mortgage companies buy and sell loans on the secondary market. When investors demand higher returns because of inflation or economic uncertainty, lenders raise their rates to keep those loans attractive. A quote you get on Monday can look different by Thursday if the markets move.
What Rate Changes Mean for Your Buying Power
Even a fraction of a percentage point changes how much house you can afford in Tamarac. Most buyers focus on the $315,000 median price, which makes sense – but the interest rate is what determines your actual monthly cost. When borrowing costs climb, your purchasing power shrinks, and you may need to look at lower price tiers to keep the payment manageable.
Comparing Monthly Payments
For illustration only: on a $300,000 mortgage, a 6% rate puts your principal and interest at roughly $1,798 per month. At 6.5%, that same loan runs about $1,896. At 7%, you’re looking at around $2,000. That $200 difference is real money, and it directly limits what you can offer on a house.
The Trade-Off Between Price and Rate
Buyers are always weighing the listing price against their borrowing cost. When rates fall, you can bid higher on a home without increasing your monthly payment. When rates rise, the math pushes you toward lower price points to keep the payment in a comfortable range.
Choosing Between Fixed and Adjustable-Rate Mortgages
The loan structure you choose sets your interest rate – and the type of government backing behind that loan changes the cost of borrowing too. Conventional, FHA, VA, and USDA loans all carry different risk profiles for lenders, which means different pricing for you.
It’s worth understanding the main structures before you sit down with a loan officer.
30-Year versus 15-Year Fixed Loans
A 30-year fixed-rate mortgage spreads payments over three decades, keeping the monthly cost lower but stacking up more total interest along the way. A 15-year fixed loan typically carries a lower interest rate, but the compressed timeline means a much higher monthly payment. Buyers who want to build equity faster and can handle the larger payment often prefer the 15-year.
How Adjustable-Rate Mortgages Work
An adjustable-rate mortgage starts with a lower introductory rate for a set period – usually five to seven years. After that, the rate adjusts annually based on market conditions, so your payment can go up or down. Buyers who plan to sell their Tamarac home or refinance before that introductory period ends sometimes use ARMs to lock in lower initial payments.
Government-Backed versus Conventional Loans
Conventional loans generally require stronger credit scores and offer competitive pricing for well-qualified buyers. FHA loans are built for buyers with lower scores or smaller down payments. VA loans provide strong terms for eligible veterans and active-duty service members. Ask your loan officer to run the numbers on each option side by side – the difference can be meaningful.
How to Qualify for the Lowest Possible Rate
Lenders save their best pricing for borrowers who present the least risk. The good news is that you have real control over several of the factors that determine where your rate lands.
Preparing your finances before you apply – even just a few months out – can translate directly into lower borrowing costs over the life of the loan.
Improving Your Credit Score
Your credit score carries more weight than any other single factor in mortgage pricing. Borrowers with scores above 740 generally see the most favorable terms; lower scores cost you a premium. In the months before your home search, pay down credit card balances and don’t open any new accounts.
Down Payments and Rate Buy-Downs
A larger down payment reduces the lender’s exposure, which often results in a better rate. You can also pay discount points at closing – an upfront fee that permanently lowers your interest rate. That trade-off makes sense if you plan to stay in the home long enough for the monthly savings to outpace what you paid upfront.
Shopping Multiple Lenders and Rate Locks
If you apply with only one lender, you take whatever they offer. Get quotes from at least three – compare the interest rates and the fees. Once you have an accepted contract and you’re comfortable with the payment, request a rate lock. That locks in your specific rate for a set period, usually 30 to 60 days, so a market move before closing doesn’t cost you.
Finding a Local Mortgage Lender in Broward County
The lender you choose matters almost as much as the rate they quote you. A smooth closing requires a responsive team that knows this market.
National call centers process loans across the entire country. They can work, but they often lack the local knowledge that matters when something unexpected comes up – and something almost always does.
Local Lenders versus National Call Centers
A local Broward County lender understands the area’s specific property types and insurance requirements. When an appraisal issue or a condo questionnaire comes up, a local loan officer usually has the contacts to resolve it quickly. Call centers often operate in different time zones and may hand your file to a different representative each time you call.
Understanding Banks, Credit Unions, and Brokers
Retail banks offer their own loan products, which can be limited in scope. Credit unions sometimes offer favorable terms to members but can run slower on processing. Mortgage brokers don’t lend their own money – they shop your application across dozens of wholesale lenders to find the best terms for your situation. Each model has its place; the right fit depends on your specific profile.
Selling a House in Tamarac When Rates Fluctuate
Tamarac homes currently spend an average of 84 days on the market, and borrowing costs are a big reason that timeline can stretch or compress. When rates shift, buyer behavior follows almost immediately.
Understanding the financing side of the transaction helps you set realistic expectations before you list.
Pricing Your House for Current Demand
When rates rise, buyers qualify for smaller loan amounts – and that shrinks the pool of people who can afford a premium price. Competitively priced homes attract the buyers who are still active; overpriced listings sit. With the average Tamarac home selling for about 96.4% of its list price, pricing accurately from day one will serve you better than testing the market with an inflated number and adjusting later.
Mortgage Rate FAQs
What are mortgage rates today in Tamarac, FL?
Mortgage rates change daily and vary based on your personal financial profile. To get an accurate number, request a specific quote or a Loan Estimate from a lender. Online averages won’t reflect the exact rate you’ll pay.
Should I wait for rates to drop before buying a home in Tamarac?
It depends on your timeline and budget. Timing the market is difficult, and when rates do drop, buyer competition tends to increase and drive prices up. If you find a home that fits your budget now, buying lets you start building equity rather than waiting on a rate move that may or may not happen on your schedule.
How much does a 1% difference in mortgage rate cost me?
More than most people expect. For illustration only, on a $300,000 loan, dropping from a 7% rate to a 6% rate saves roughly $200 a month in principal and interest. Over a 30-year term, that adds up to tens of thousands of dollars.
How do I get the best mortgage rate as a buyer in Tamarac?
Improve your credit score, reduce your existing debt, and save for a larger down payment. Then apply with multiple lenders and compare their Loan Estimates side by side – don’t just take the first offer.
How do I choose a mortgage lender in Tamarac, FL?
Look for a local professional in Broward County who communicates clearly and has a track record of closing on time. Compare options among local mortgage brokers, credit unions, and direct lenders before defaulting to a national call center.
What credit score do I need to get a good mortgage rate in Tamarac?
Conventional lenders typically reserve their best pricing for borrowers with scores of 740 or higher. You can still get a mortgage with a lower score, but you’ll likely pay a higher rate or need to explore government-backed options like FHA loans.
When should I lock in my mortgage rate when buying a home in Tamarac?
Lock in once you have an accepted offer and you’re comfortable with the monthly payment your lender quoted. A rate lock protects you from market increases during the 30 to 60 days it typically takes to close.
Local Advice for Buying or Selling in Tamarac
A real estate transaction involves a team – and it starts before you ever pull up a mortgage calculator. Talking to a local agent first gives you context on current neighborhood trends, property values, and what closing timelines look like in Tamarac right now.
A good agent can also connect you with local lenders who’ve already proven they can get buyers to the closing table on time. That referral is worth more than it sounds.